The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Dreaming of hitting the open road on a brand-new motorcycle? Financing your motorcycle in Australia comes with several options to suit different needs and budgets. With the right loan, you can make your dream bike more accessible. However, choosing the right loan is crucial to ensure it aligns with your financial situation.
The importance of securing the best loan rates cannot be overstated. Not only does it impact your monthly repayments, but it also affects the total interest you'll pay over the life of the loan. Understanding the basics will empower you to make informed choices and ultimately save money.
This article will guide you through the differences between secured and unsecured loans, helping you determine the best choice for you. By the end, you'll have a clearer understanding of how each option can affect your finances and what steps you can take to get the best possible rates.
Understanding Secured Loans for Motorbike Financing
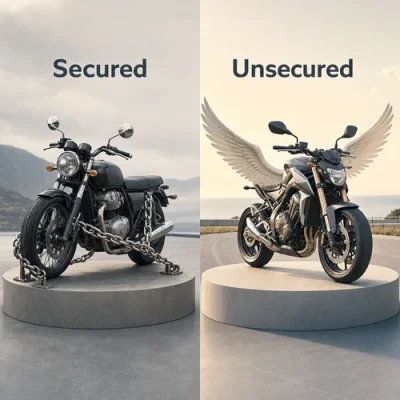
When it comes to financing your motorbike, secured loans offer a unique set of benefits and considerations. But what exactly is a secured loan? Simply put, this type of loan requires the borrower to provide an asset as collateral. This asset, often the motorcycle itself, acts as security for the lender, reducing their risk in the event of non-payment.
In Australia, secured loans are commonly used for large purchases such as homes, cars, and of course, motorbikes. By using the bike as collateral, you often gain access to lower interest rates compared to unsecured loans. This can make a significant difference in your monthly repayments and the total cost of the loan over time.
However, there are advantages and disadvantages to consider. On the plus side, secured loans can offer more attractive terms due to the reduced risk for lenders. On the downside, if you fail to meet your repayments, the lender has the right to repossess the motorbike. This makes it crucial to weigh your options carefully and ensure you can comfortably meet the repayment terms.
Understanding Unsecured Loans
Unsecured loans are a popular option for financing a motorbike, especially for those who prefer not to commit any asset as collateral. An unsecured loan doesn't require you to provide your motorcycle or any other asset as security. This means that the lender trusts you to repay the loan based on your creditworthiness and financial history.
The key difference between unsecured and secured loans lies in the requirements and risks involved. Without collateral, unsecured loans tend to carry higher interest rates because they present a higher risk to lenders. The approval process heavily relies on your credit score and income stability, making it essential to have a strong financial profile to secure favourable terms.
Opting for an unsecured loan comes with its own set of advantages and disadvantages. On the positive side, you won't risk losing your bike if you're unable to keep up with repayments. However, the higher interest rates and potentially shorter loan terms mean your monthly repayments could be more significant. Weighing these pros and cons carefully is essential to decide if an unsecured loan is the best fit for your financial situation and motorbike aspirations.
Comparing Secured and Unsecured Loans
When navigating the world of motorbike financing, understanding the differences between secured and unsecured loans is crucial. A key factor distinguishing these loans is the interest rates. Secured loans generally offer lower interest rates as the lender's risk is mitigated by the asset acting as collateral. This security allows lenders to pass on the reduced risk to borrowers through more competitive rates. In contrast, unsecured loans, lacking such guarantees, often come with higher interest rates to buffer the lender's increased risk.
Repayment terms also vary significantly between the two options. Secured loans typically provide longer repayment periods, allowing for smaller, more manageable monthly payments. This flexibility can be appealing if you're looking to stretch your budget over an extended timeframe without the fear of losing your vehicle. However, unsecured loans might offer shorter terms, leading to larger monthly payments but the upside of quicker debt clearance.
Each loan type also carries different risk factors. With secured loans, the primary risk is the potential loss of the asset in case of default. For unsecured loans, while your assets are safe, the risk revolves around financial strain due to higher repayments and interest rates. Carefully evaluating these aspects and how they align with your financial situation and risk tolerance is essential to making an informed decision.
How to Decide on the Best Loan for You
Choosing the right loan for your motorbike purchase is a critical decision that depends on several personal factors. First and foremost, consider your budget. Understanding how much you can comfortably afford each month will help you decide between secured and unsecured options. Secured loans might offer lower monthly payments, but weigh this against the risk of losing your bike if you default.
It's also important to consider your future financial plans. Are you expecting any significant changes in income or expenses? If you foresee a stable financial future, a longer-term secured loan could be beneficial. However, if you predict financial flux, a smaller, short-term unsecured loan might be less risky.
Asset ownership is another crucial factor. Consider whether you want to use your motorbike or another asset as collateral. If keeping your options open appeals to you, an unsecured loan could be more suitable.
Ask yourself questions such as, "How will this loan fit into my current and future financial commitments?" and "What is my risk tolerance regarding asset use?" Thankfully, plenty of resources are available for further research. Websites offering loan comparisons, financial advisors, and banking institutions can provide insight and advice tailored to your situation.
Tips for Applying for a Motorbike Loan
Before diving into the application process for a motorbike loan, it's essential to prepare thoroughly to increase your chances of securing favourable terms. Start by organising your financial documents, such as proof of income, identification, and any relevant financial statements. Having these ready can streamline the application process and demonstrate your reliability to potential lenders.
Your credit score plays a pivotal role in determining not only your eligibility for a loan but also the interest rates and terms you may be offered. It's worthwhile to check your credit score beforehand and take steps to improve it if necessary, such as paying down existing debts or correcting any errors on your credit report. A higher credit score can make a significant difference in the offers you receive.
Once prepared, take the time to shop around for the best loan offers. Compare rates and terms from various lenders, including banks, credit unions, and online lenders. Be sure to understand all the conditions and fees associated with each offer, as these can impact the total cost of the loan.
Negotiating with lenders can also be an effective strategy. Don't hesitate to discuss your needs and financial situation to potentially secure better terms. Some lenders may be willing to adjust interest rates or repayment conditions based on your negotiations, so it pays to ask.
Conclusion
In summary, understanding the key differences between secured and unsecured loans is critical to making an informed decision when financing your dream motorcycle. Secured loans typically offer lower interest rates and longer repayment terms due to the collateral involved, such as your motorbike. However, the risk of asset repossession in default situations cannot be overlooked. On the other hand, unsecured loans, though free from collateral risk, often come with higher interest rates and potentially shorter terms, challenging your monthly budget.
As you navigate your loan options, take the time to thoroughly assess all available choices. Evaluate your financial situation, future plans, and risk tolerance to determine which type of loan aligns best with your personal circumstances. Remember, the goal is to find a loan solution that supports not just your current lifestyle but also your long-term financial health.
Achieving your motorbike dreams is exciting, and choosing the right financing option plays a significant role in making it sustainable. By taking a measured and well-researched approach to loan selection, you can pave the way toward fulfilling your aspirations wisely. As you embark on your financial journey, feel empowered to make choices that align closely with your dreams and financial goals, ensuring a smooth ride toward owning your dream bike.
Published: Friday, 27th Jun 2025
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.