Bike Loan Finance Online Vehicle Lease Repayment Calculator
Explore potential car leasing costs with our Car Lease Calculator. Estimate monthly payments and test different interest rates, lease terms and residual (balloon) amounts to see how these variables may influence your repayments and overall leasing costs.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual costs and repayments may differ.
Car Lease Details:
Important!
Car Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Lease Amortisation Calculator
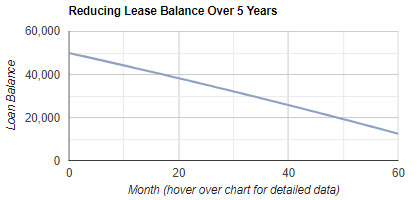
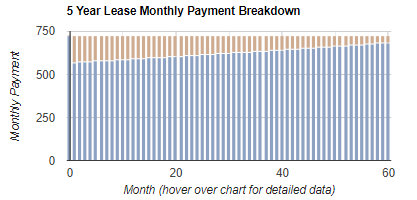
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Vehicle Lease Repayment Calculator
Our Vehicle Lease Repayment Calculator helps you estimate monthly lease repayments for a motor vehicle by modelling three key variables: interest rate, lease term, and the residual or balloon amount payable at the end. It’s important because small changes to any of these inputs can materially affect cash flow, total interest over the term, and the end-of-lease obligation, helping you compare scenarios before you speak with a lender or novated leasing provider.
How to complete the form for the best result:
1. Purchase Price
Enter the total amount you want financed for the vehicle. Include relevant upfront costs you intend to roll into the lease (for example, on-road costs or insurance where applicable). Use whole numbers only (no decimals, commas, or dots).
2. Balloon or Residual Value (percent of purchase price)
Select the residual percentage. A higher residual generally reduces the monthly payment but increases the amount left owing at the end, which can increase overall cost across the term. Choose a residual that matches your intended end-of-lease plan (keep, refinance, or sell).
3. Term of Loan (years)
Choose the number of years. Longer terms usually reduce monthly repayments but can increase total interest paid. Select a term that suits how long you expect to keep the vehicle and your budget tolerance.
4. Interest Rate (per annum)
Select an interest rate to simulate. Use a conservative rate when stress-testing affordability, because your actual rate may differ depending on lender policy and your circumstances.
5. Calculate
Click calculate to generate your estimated monthly lease repayment and amortisation visuals.
How to interpret the results:
1. Monthly repayment estimate: Use this as a budgeting guide and compare scenarios by adjusting term, rate, and residual.
2. Amortisation charts: Review how the balance reduces over time and how much of each payment is interest versus principal; this highlights when interest costs are highest and the impact of a larger residual.
ASIC compliance note: This guide is general information only and does not consider your objectives, financial situation or needs. Consider the full lease contract, fees, taxes, insurance, maintenance, and end-of-lease options before deciding, and consider getting personal advice if needed.
When contemplating the purchase of a motorcycle in Australia, obtaining a loan might be a necessary step for many. Loan pre-qualification can serve as a valuable tool in this process. Essentially, pre-qualification provides an estimate of how much financing you might be eligible for based on your financial situation. - read more
Motorcycle loan repayments are shaped by the amount borrowed, interest rate, loan term, fees, repayment frequency and any balloon or residual payment. Understanding how these factors work together can help Australian riders compare finance options and estimate affordability before applying. - read more
Applying for motorbike finance usually involves more than choosing a bike and requesting a loan amount. Australian lenders may assess your identity, income, expenses, credit history, employment, residency status and motorcycle details before deciding whether to offer finance. - read more
The experience of riding a motorbike is unmatched, offering a sense of freedom and adventure. But along with the excitement comes the responsibility of ensuring that both you and your bike are protected. - read more
Fresh Australian Bureau of Statistics lending data has delivered a mixed signal for Australians weighing up motorcycle finance: road-vehicle borrowing rose in the September quarter, even as broader personal loan demand softened and interest-rate pressure remained firmly in the background. - read more
The Reserve Bank of Australia's latest parliamentary testimony has given motorcycle buyers a timely reminder that borrowing conditions remain sensitive to inflation, lender pricing and household budget pressure. Governor Michele Bullock told a Senate economics committee on 28 October 2026 that inflation has remained above target, the cash rate has risen by a cumulative 100 basis points this year, and the Monetary Policy Board will meet again next week to assess whether the tightening already delivered is enough. - read more
Fresh RBA credit data has given motorcycle buyers another reason to keep their finance planning practical. The latest lending indicators point to a household borrowing market that remains active, even as consumers continue to face elevated living costs and lenders maintain close checks on affordability. For riders, that means competition for finance has not disappeared, but neither has the need to prove that a loan is manageable. - read more
Financial markets have entered September with a more cautious view of how quickly borrowing costs may fall. Recent market coverage suggests investors are less willing to assume a smooth run of Reserve Bank rate cuts, with inflation progress still uneven and consumer activity proving more resilient than many borrowers might have expected. - read more